All Categories
Featured
Direct Consumer Advice for Choosing Coverage
One of the most attractive features is the ability to access the cash worth through policy loans and withdrawals, typically on a tax-free basis, supplied the policy is structured correctly and remains in force. Policy loans are usually ruled out gross income. Withdrawals as much as the quantity of premiums paid (your cost basis) are usually tax-free.
Senior Dental Vision HearingIt's crucial to understand that if the policy lapses or is surrendered, impressive loans and gains might end up being taxable. The adjustable premium payments and potential survivor benefit choices supply a degree of versatility not constantly found in other irreversible life insurance items. While focusing on cash growth, the policy still supplies a vital survivor benefit for recipients, offering financial protection for your enjoyed ones.
The "best IUL policies for cash build-up" will typically include competitive caps, involvement rates, and manageable internal costs. The "finest business for IUL" for retirement planning may also offer favorable loan provisions.
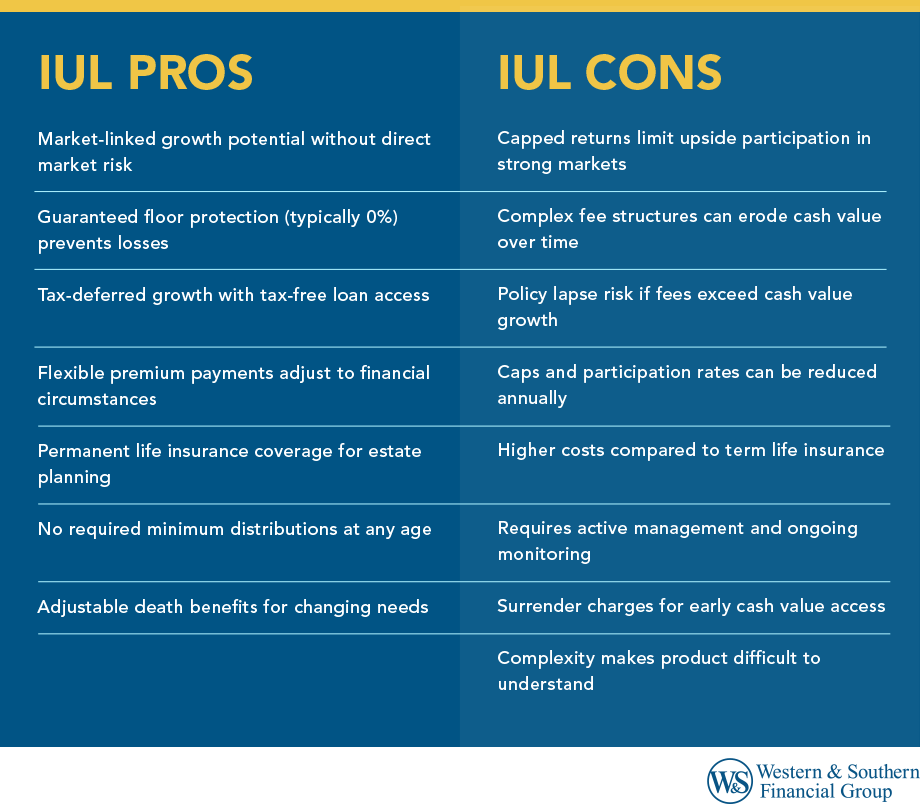
Due to the fact that today's cap is not the entire story, our contrast of IUL renewal cap rates: F&G vs Pacific Life and Lincoln looks at how caps have actually changed gradually. While IUL offers engaging potential benefits, it's vital to approach it with a clear understanding of the associated threats and costs.
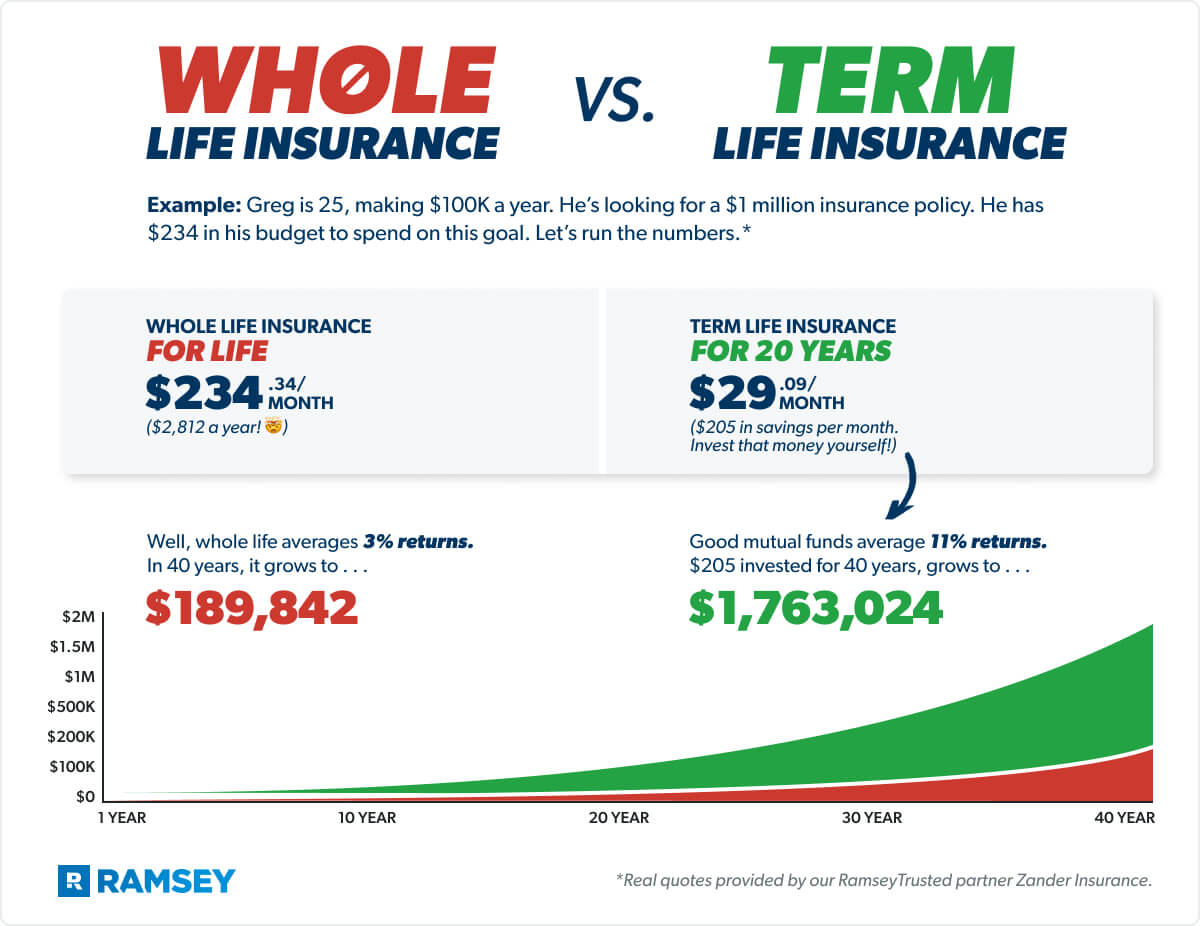
Term vs Whole Life Insurance Basics
IUL policies are naturally more complicated than term life or even traditional whole life. Policy illustrations, which project future money value growth, are based on numerous presumptions about index efficiency, crediting rates, policy expenses, and loan usage.
IUL policies have various internal charges that lower money worth growth. These can consist of: The charge for the pure death advantage defense.
Costs for any additional benefits added to the policy. Fees applied if you surrender the policy or withdraw significant quantities, typically within the very first 10-15 years.
While the flooring secures versus direct market * losses *, it doesn't ensure positive returns. If the linked index carries out inadequately or stays flat for prolonged durations, your cash worth may just make the floor rate (frequently 0%). After policy costs are deducted, the money worth might potentially decrease in such years.
Even in booming market years, your credited interest won't exceed the cap. Participation rates below 100% more minimize the credited interest relative to the index gain. Carriers can sometimes change non-guaranteed components like caps and participation rates over the life of the policy (within legal limits), which might impact long-term efficiency.

Latest Posts

A Comprehensive Guide to 2026 Medicare Benefits
Exploring How Whole Life Insurance Functions
Finding the Best Medicare Supplement Policies for 2026