All Categories
Featured

A Comprehensive Guide to 2026 Medicare Benefits
That flexibility can be huge if your earnings changes from year to year, or you go through a big life event (such as divorce or momentary work leave) and still wish to keep your policy in force. However it also indicates you'll need to pay closer attention to your policy gradually.

This table highlights the most significant distinctions: Both whole life insurance coverage and indexed universal life offer you with irreversible coverage that constructs cash value, but how that money worth grows is quite different. Whole life insurance coverage usually has actually guaranteed development at a fixed rate, while IUL has the capacity for higher returns due to the fact that its cash value is tied to a market index.
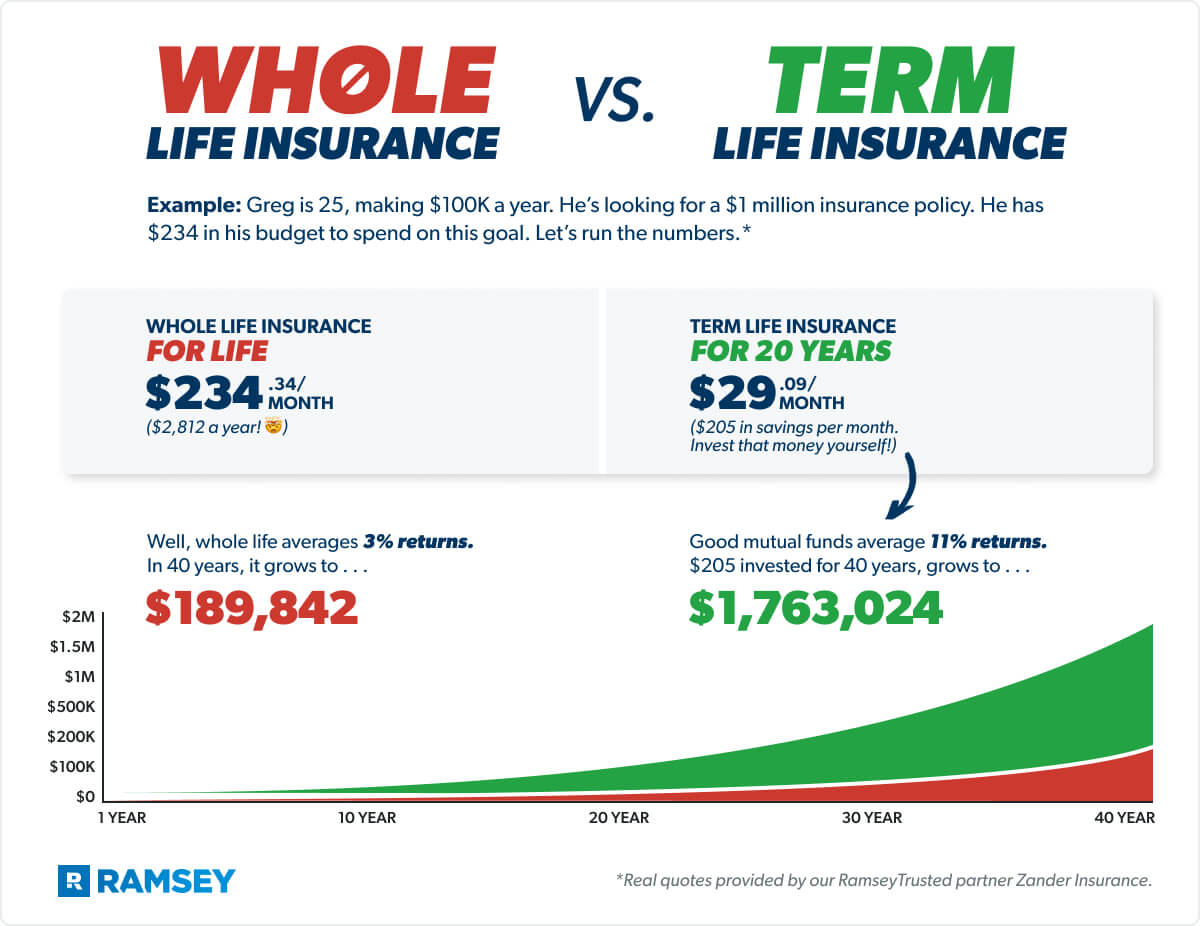
Insurance in National City CATerm life insurance coverage is normally the most affordable and easiest type of life insurance to get. It doesn't develop cash worth, however you get a guaranteed death benefit for a set amount of time, frequently at a portion of the cost of an IUL policy. You can think about a variable universal life insurance policy as one step above an IUL policy in terms of risk and reward.
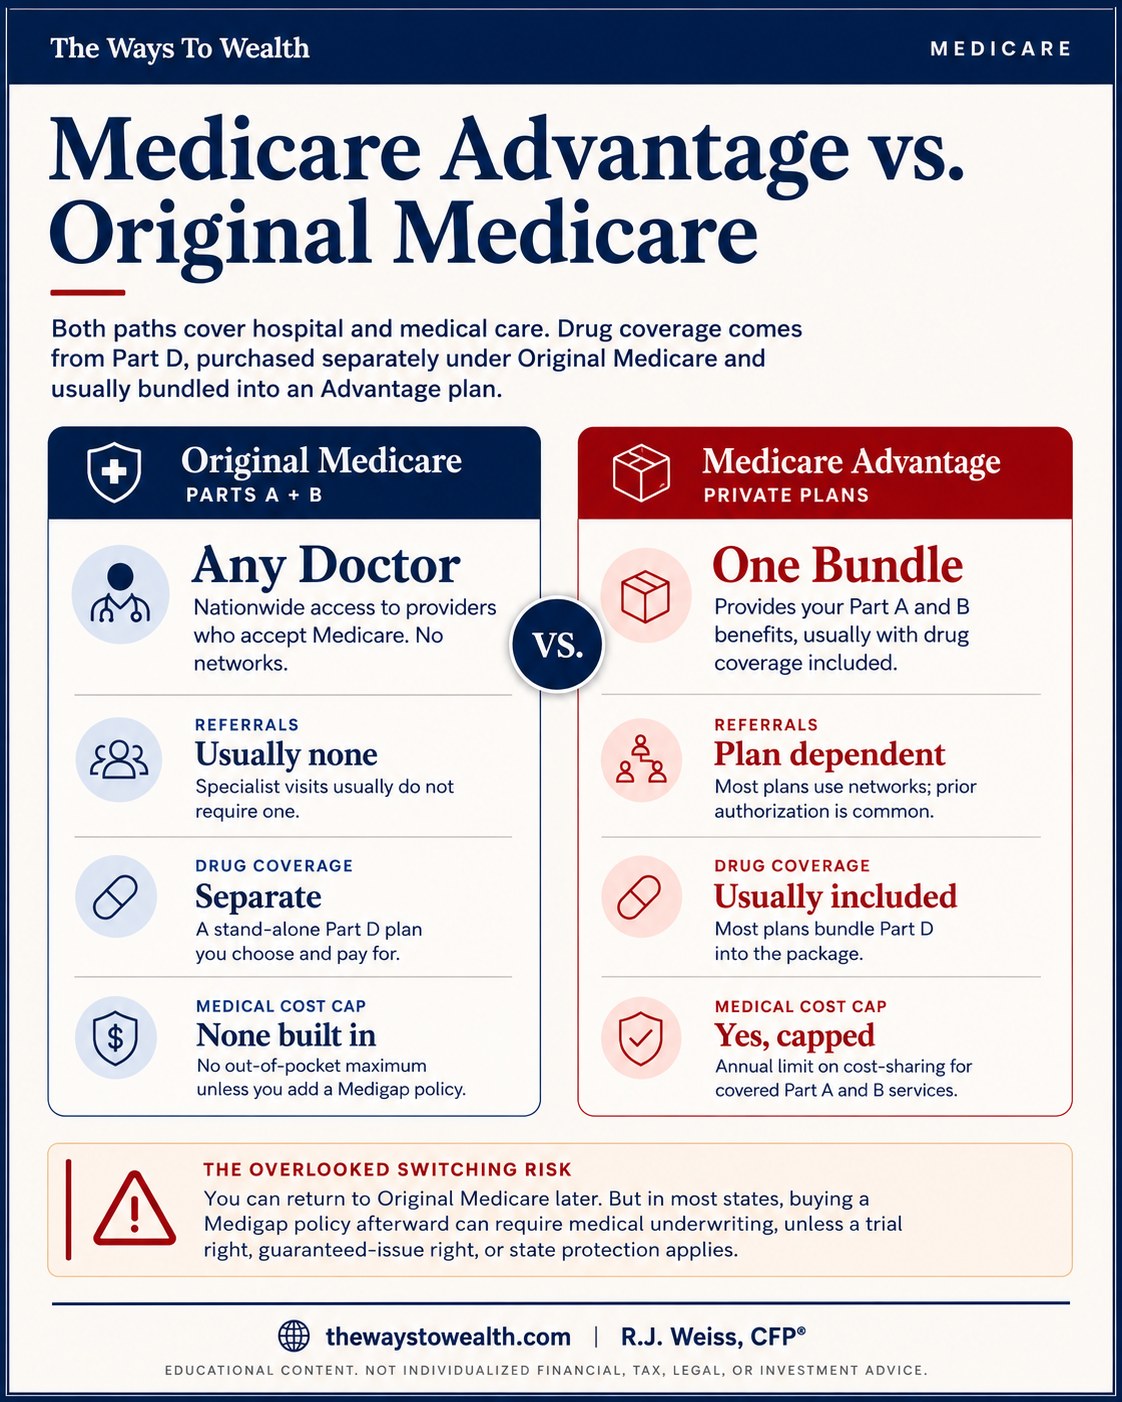
This indicates you'll have greater development potential but also the possibility of investment losses. Like any monetary product, indexed universal life insurance coverage has benefits and trade-offs. If your primary goal is just replacing your income for your household, a term life insurance policy is normally easier and far more economical.
Choosing Whole Life versus Term Benefits
Common costs might include:, which generally increases as you age for handling the policy subtracted from your payments if you include functions like long-term care or persistent disease advantages if you cancel the policy throughout its early years Before you buy an indexed universal life policy, the insurer will usually supply an illustration demonstrating how your policy could carry out with time.

Latest Posts
A Comprehensive Guide to 2026 Medicare Benefits
Exploring How Whole Life Insurance Functions
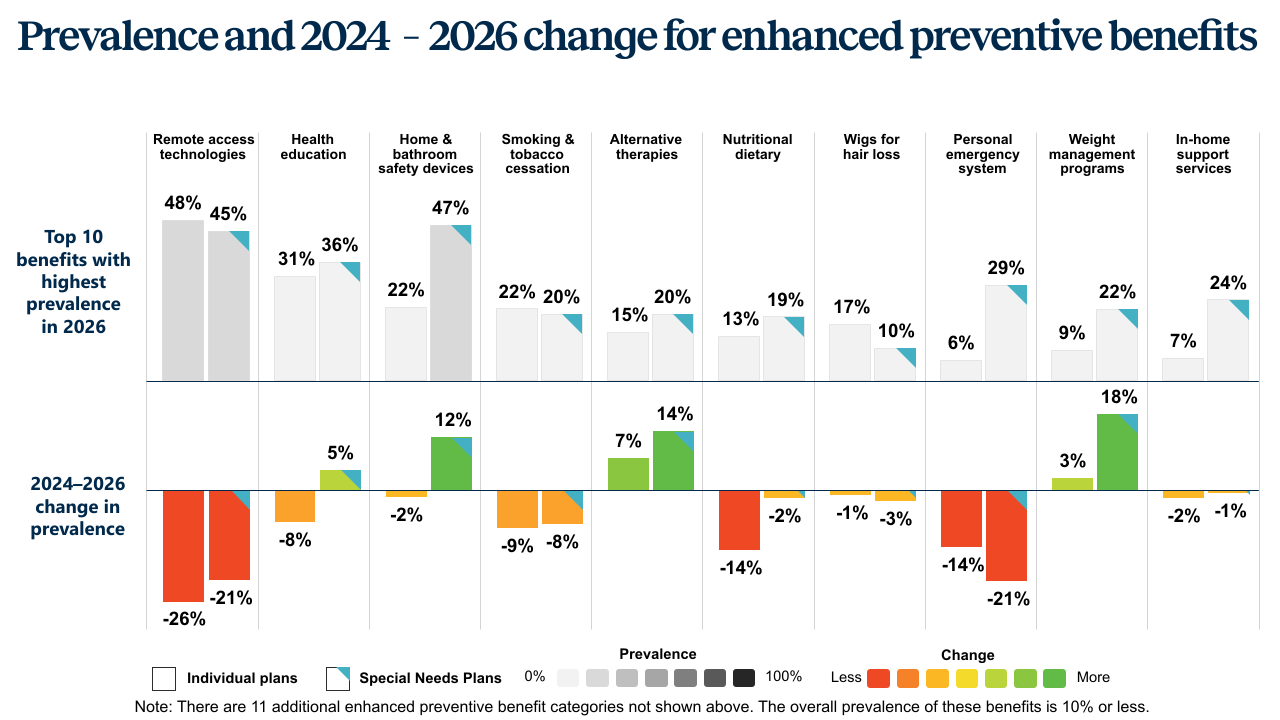
Finding the Best Medicare Supplement Policies for 2026