All Categories
Featured
Analyzing PPO Provider Access versus Monthly Costs
Table of Contents
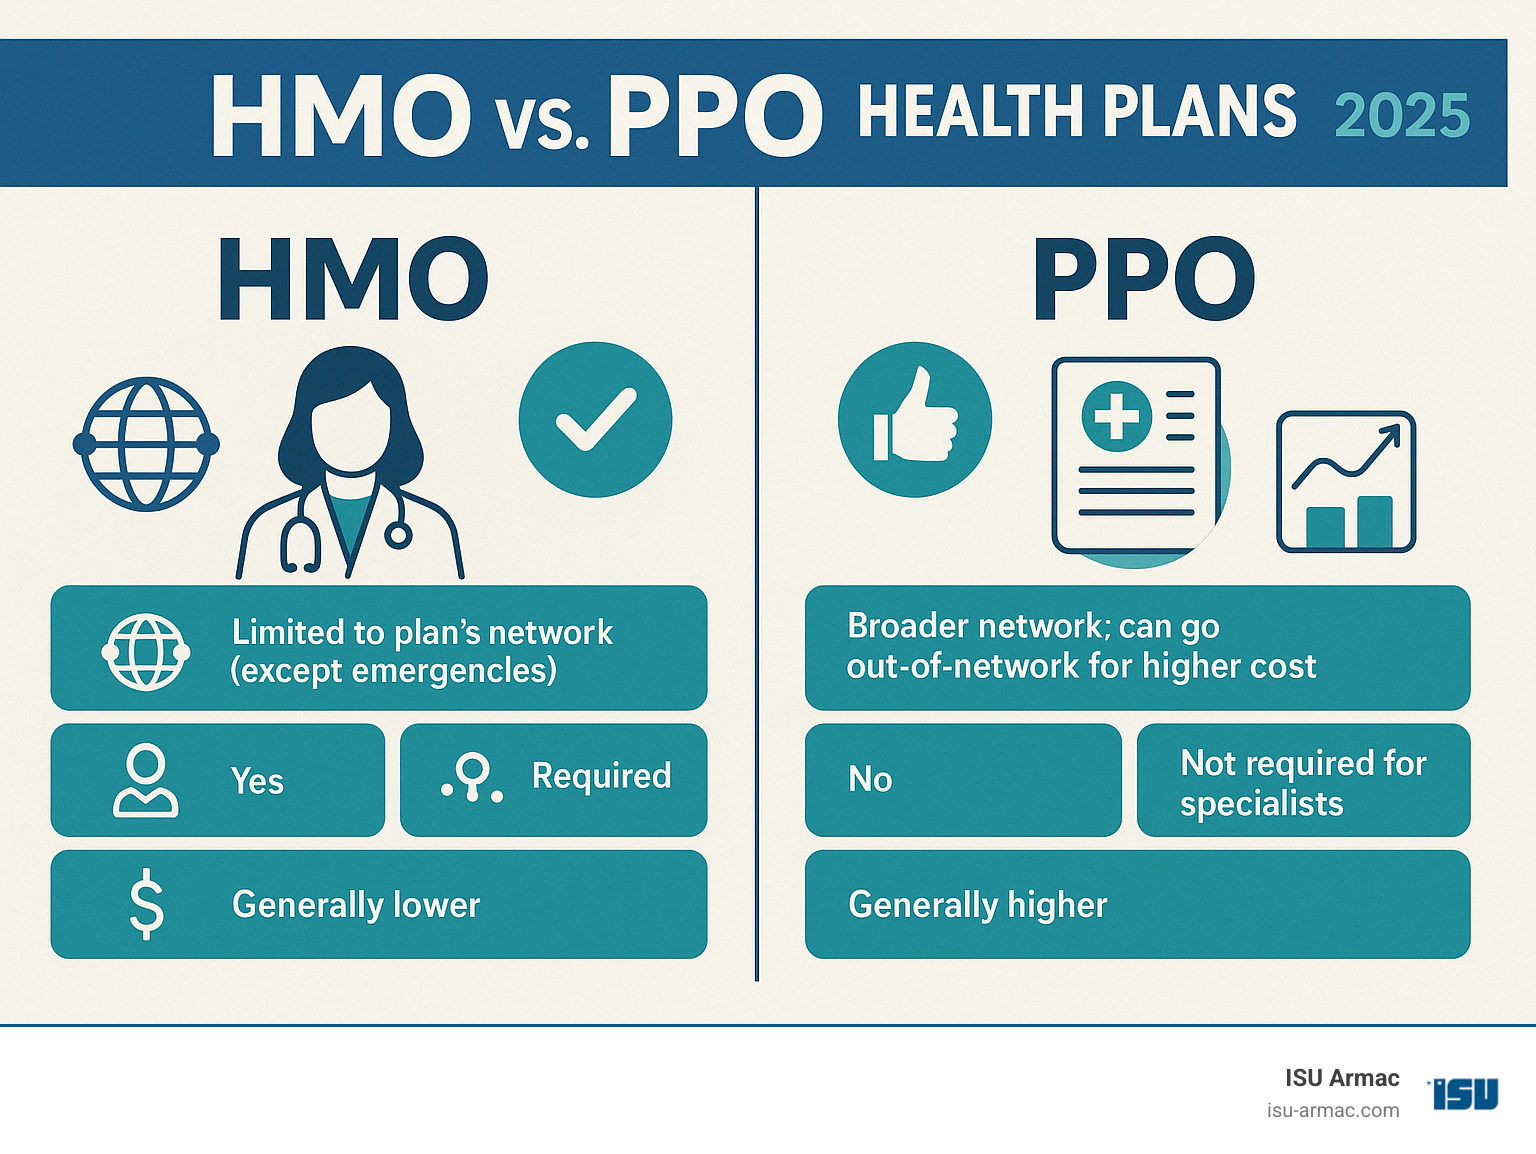
Premiums are normally lower for HMO plans, and there is generally no deductible or a low one. Some HMO strategies, including those offered by Medical Mutual, do not require you to pick a PCP or have a recommendation to see a professional. For more HMO specifics, read our About HMO Strategies short article.
They also include a network of suppliers, however there are fewer restrictions on seeing non-network service providers. In addition, your PPO insurance coverage will pay if you see a non-network service provider, although it might be at a lower rate. Here are some essential features: You can see the medical professional or professional you 'd like without having to see a PCP.
Your advantages will be much better if you remain in the PPO network. As pointed out above, Distinctions between HMO (Health Maintenance Organization) and PPO (Preferred Service provider Company) plans consist of network size, capability to see professionals, costs, and out-of-network coverage.
Optimizing IUL Growth Potential in Retirement
However, PPOs usually use higher flexibility in seeing experts, have larger networks than HMOs, and provide some out-of-network protection. Here are the contrast points in more detail. A defining function of HMO and PPO strategies is that they both have networks. Networks are one method to lower health care expenses network service providers agree to provide discount rates in exchange for access to a health insurance's members.
In basic, PPO networks tend to be broader, consisting of more doctors and hospitals than HMO strategies, providing you more choice. Networks will vary from insurance company to insurance provider, and plan to plan, so it's best to research each plan's network before you decide. Most HMOs will need you to select a main care physician, who will be the main point of contact for your healthcare.
Expenses for experts will not be covered without a PCP referral. On the other hand, PPOs tend not to require selection of a PCP, and you can typically see a specialist without a referral, and still have actually these costs covered. For both PPO and HMO strategies, your expenses for care will be most affordable if you get it from in-network suppliers.
For HMOs, out-of-network services are usually not covered at all, other than for emergency situations. PPOs vary from HMOs because PPO plans will typically offer some protection for these types of services, however coverage for in-network suppliers will be much better. The additional protection and flexibility you receive from a PPO implies that PPO plans will generally cost more than HMO plans.
Low-Cost Life Quotes for Veterans
Another expense to consider is a deductible. This is the amount of healthcare costs you must pay before your plan begins to cover your expenses. Not all HMOs have deductibles, but when they do, they tend to be lower than PPO deductibles. You can learn more about health insurance expenses in our Understanding Health Insurance Coverage Expenses article.
49% of covered workers had PPO plans in the study, while HMOs covered 16%. When it pertains to your own health insurance choice, it may seem like a cliche, but when picking between an HMO or PPO strategy, it is not necessarily about which is better, but which is finest for you.
If your monetary scenario determines that cost is most crucial, you might seriously think about going with an HMO plan. Normally speaking, expenses for HMO strategies will be less.
Insurance in Menifee CAUnlike most HMO health insurance, you will not likely need to select a main care physician, and you won't typically need a recommendation from that doctor to see an expert. A PPO network will likely be larger, providing you a greater selection of in-network physicians, experts, and facilities to pick from.
Strategic Wealth Strategies with Modern Life Insurance
With HMOs, out-of-network protection will generally be limited to emergencies; non-emergency services are not generally covered at all. To help you weigh the benefits and drawbacks laid out above, here's a fast summary of them: With any strategy, check the company network to see if your preferred companies remain in the plan's network, considering that staying in-network will save you cash.

You might discover that the specific HMO strategy you're considering includes your favored service providers, or a minimum of enough of them to meet your requirements. If you're thinking about a Medical Mutual plan, you can examine our networks before you apply. For pointers on picking the very best medical insurance plan for your requirements, see our post on Comparing Health Insurance Coverage Plans.

Latest Posts
Securing the Individual Health Plan Rates
Building Family Security with Whole Life Insurance
Final Expense and Burial Insurance Options